Main residence: selling without capital gains tax
Selling your home is normally exempt. The calculator is set to “main residence” and mainly shows what you keep after costs and the mortgage.
Up to date: coefficients from the 2026 budget law and the 2026 tax scale.
Calculate my taxOnly on PlusValue.lu
Don’t sell a month too early. We’ll remind you.
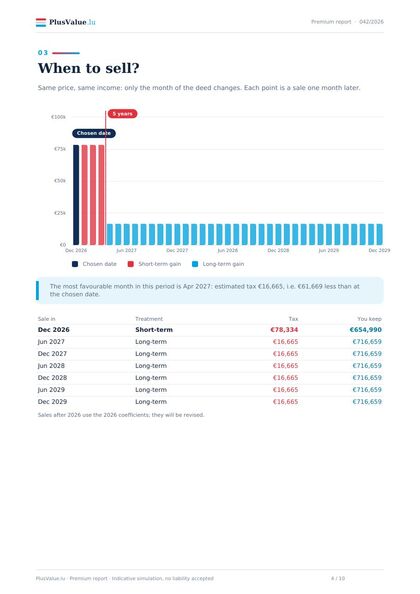
Selling just before the 5-year mark can cost tens of thousands of euros in tax. The calculator works out the exact month your sale becomes a long-term gain, and, if you wish, emails you 30 days before, with the saving in euros.
- 1Simulate your saleOne minute, no sign-up.
- 2We work out your dateThe first month with the half rate and the allowance.
- 3You tick “Remind me”And get an email 30 days before, with the tax before and after.
Free · only with your consent · one-click unsubscribe
New · Premium report
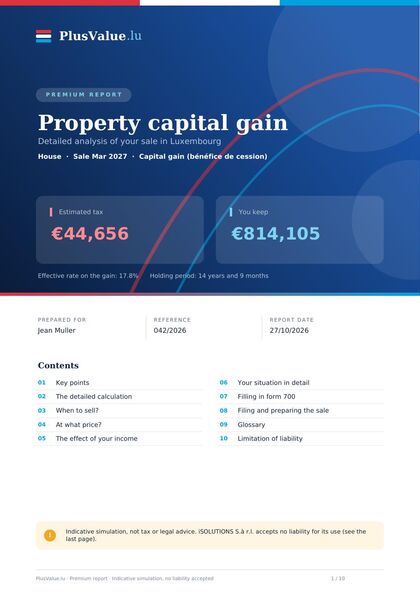
Your complete sale file, ready for your tax return
After your free simulation, order a detailed PDF report of about ten pages, produced automatically from your data.
- The detailed calculation, article by article
- Form 700 filled in line by line, with the boxes of form 100
- When to sell: the tax month by month over 3 years
- The tax by sale price and by income
- Your situation (inheritance, main residence, non-resident…) and the document checklist
The report is offered at the end of the simulation. Indicative simulation, not tax or legal advice.

Conditions of the exemption
The gain is exempt (art. 102bis L.I.R.) if the home is your usual residence since you bought or completed it, or for at least the five years before the sale. The five-year condition does not apply if you moved for family or work reasons.
A home you have left remains exempt if it is sold by 31 December of the year after you moved out, or later if you have no other home available.
Land: outbuildings and the normal plot around the house are included. A separate or unusually large plot is assessed separately.
Even when exempt, the sale must appear on your tax return. Untick “main residence” in the calculator to see the tax that would be due without the exemption.
Sell with iMMOSOLUTIONS
Your result is ready. For the sale itself, the agency behind PlusValue.lu combines local experience with digital tools that traditional agencies do not have.
- 1,000+
- completed transactions
- 2006
- in Howald, licensed agency
- 1st
- agency in Luxembourg with its own iPhone and Android app
Maximum visibility
athome.lu, immotop.lu, wortimmo.lu, the Luxemburger Wort, Facebook and Instagram campaigns, and a listing in 5 languages.
AI for the right price
Market analysis and live tracking of competing listings, to set the right price and adjust it at the right time.
Your seller area
Views, viewings, offers and counter-offers in real time, documents and messages, around the clock in the app.
100% digital, up to the deed
Mandate, offer and sale agreement signed online with an eIDAS-compliant electronic signature.
How the calculation works
In Luxembourg, the sale of a private property is taxed according to how long you owned it. The calculator follows the same steps as the tax return (form 100 with its annex, and form 700).
Acquisition price
Purchase price, purchase costs (registration duties, notary) and capital improvements. For inherited or gifted property: the price paid at the last purchase for consideration.
Revaluation
If you sell more than 5 years after buying, each expense is multiplied by the coefficient for its year. It corrects for inflation: the older the purchase, the lower the taxable gain.
Gain
Sale price, minus the selling costs you pay (mainly agency commission), minus the revalued acquisition price. A loss cannot be offset against other income.
Allowances
For a capital gain: €50,000 per person, €100,000 for a couple taxed jointly, over ten years. Plus €75,000 for your parents’ last residence inherited in direct line.
Tax
Capital gain: half the global rate, meaning half the average tax rate on your total income including the sale (at most 21% plus the employment fund contribution). Speculative gain: progressive scale up to 42% plus the contribution.
Speculation or capital gain: the 5-year rule
If no more than five years pass between purchase and sale, the profit is a speculative gain (art. 99bis L.I.R.): it is added to your income for the year and taxed at the normal scale, with no revaluation or allowance. After that, it is a capital gain (art. 99ter L.I.R.) taxed at half the global rate.
The dates that count are those of the notarial deeds. A few months can halve the tax: the calculator shows when waiting pays off.
For reference, a temporary measure shortened the period to two years and applied a quarter of the global rate to sales between 1 January 2024 and 30 June 2025 (until 30 September 2025 if the sale agreement was registered by 30 June 2025). It has ended.
Main residence
The gain on your main residence is exempt (art. 102bis L.I.R.) if you have lived there since buying or completing it, or for at least the five years before the sale. The five-year condition does not apply if you move for family or work reasons.
A home you have left remains exempt if it is sold by 31 December of the year after you moved, or later if you have no other home available. Outbuildings and the normal plot around the house are included; a separate or very large plot is assessed separately.
Inherited or gifted property
For property received free of charge, the tax office does not use the value at death: it uses the price paid by the last owner who bought it, revalued with the coefficient of that purchase year (circular L.I.R. no. 99ter/1bis). Find your parents’ purchase deed.
If it was your parents’ last main residence, a €75,000 allowance is added to the ten-year allowance. It is not doubled for couples and applies to one property only. Between heirs, each declares their share with their own allowances: use the “Your share of the property” field.
Revaluation coefficients
The table that applies depends on the year of sale. Since 2026, it is the table from the 2026 budget law (art. 102 (6) L.I.R.). For a sale in 2025, the previous table applies.
| …0 | …1 | …2 | …3 | …4 | …5 | …6 | …7 | …8 | …9 | |
|---|---|---|---|---|---|---|---|---|---|---|
| 1910 | 206.57* | 93.90 | ||||||||
| 1920 | 50.26 | 51.43 | 55.20 | 46.66 | 41.55 | 39.71 | 33.51 | 26.55 | 25.47 | 23.71 |
| 1930 | 23.29 | 25.97 | 29.91 | 30.07 | 31.25 | 31.83 | 31.66 | 29.99 | 29.15 | 29.24 |
| 1940 | 26.89 | 17.34 | 17.34 | 17.34 | 17.34 | 13.82 | 10.97 | 10.55 | 9.88 | 9.38 |
| 1950 | 9.05 | 8.38 | 8.24 | 8.25 | 8.17 | 8.18 | 8.14 | 7.78 | 7.73 | 7.70 |
| 1960 | 7.68 | 7.63 | 7.56 | 7.35 | 7.13 | 6.90 | 6.72 | 6.56 | 6.36 | 6.22 |
| 1970 | 5.95 | 5.68 | 5.40 | 5.09 | 4.65 | 4.20 | 3.82 | 3.58 | 3.47 | 3.32 |
| 1980 | 3.13 | 2.89 | 2.65 | 2.43 | 2.30 | 2.24 | 2.23 | 2.23 | 2.20 | 2.13 |
| 1990 | 2.05 | 1.99 | 1.93 | 1.86 | 1.82 | 1.79 | 1.76 | 1.74 | 1.72 | 1.70 |
| 2000 | 1.65 | 1.61 | 1.58 | 1.55 | 1.51 | 1.48 | 1.44 | 1.41 | 1.36 | 1.36 |
| 2010 | 1.33 | 1.28 | 1.25 | 1.23 | 1.22 | 1.22 | 1.22 | 1.19 | 1.18 | 1.16 |
| 2020 | 1.15 | 1.12 | 1.06 | 1.02 | 1.00* |
* 1918 and earlier · 2024 and later
| …0 | …1 | …2 | …3 | …4 | …5 | …6 | …7 | …8 | …9 | |
|---|---|---|---|---|---|---|---|---|---|---|
| 1910 | 195.42* | 88.84 | ||||||||
| 1920 | 47.55 | 48.66 | 52.22 | 44.14 | 39.31 | 37.56 | 31.70 | 25.12 | 24.09 | 22.43 |
| 1930 | 22.03 | 24.57 | 28.29 | 28.45 | 29.56 | 30.11 | 29.96 | 28.37 | 27.58 | 27.66 |
| 1940 | 25.44 | 16.40 | 16.40 | 16.40 | 16.40 | 13.08 | 10.38 | 9.99 | 9.35 | 8.88 |
| 1950 | 8.56 | 7.92 | 7.79 | 7.81 | 7.73 | 7.74 | 7.70 | 7.36 | 7.31 | 7.28 |
| 1960 | 7.26 | 7.21 | 7.15 | 6.95 | 6.74 | 6.52 | 6.36 | 6.21 | 6.02 | 5.89 |
| 1970 | 5.62 | 5.37 | 5.11 | 4.82 | 4.40 | 3.97 | 3.62 | 3.39 | 3.29 | 3.14 |
| 1980 | 2.96 | 2.74 | 2.50 | 2.30 | 2.18 | 2.12 | 2.11 | 2.11 | 2.08 | 2.01 |
| 1990 | 1.94 | 1.88 | 1.82 | 1.76 | 1.72 | 1.69 | 1.67 | 1.64 | 1.63 | 1.61 |
| 2000 | 1.56 | 1.52 | 1.49 | 1.46 | 1.43 | 1.40 | 1.36 | 1.33 | 1.29 | 1.28 |
| 2010 | 1.26 | 1.22 | 1.18 | 1.16 | 1.16 | 1.15 | 1.15 | 1.13 | 1.11 | 1.09 |
| 2020 | 1.09 | 1.06 | 1.00* |
* 1918 and earlier · 2022 and later
What the calculator does not cover
- Rented property: depreciation deducted while it was let reduces the acquisition price. Ask your accountant for the amount.
- Non-residents: a sale of property located in Luxembourg is taxed there. Without being treated as a resident, class 1 normally applies; the tax treaty with your country settles the rest.
- Companies, developers, property dealers: these sales are business income or corporate tax.
- Several sales: an allowance used on a sale in the last ten years reduces what is left; enter it under advanced options.
Questions
Do I have to declare the sale of my main residence?
Yes. The gain is exempt if the conditions are met, but the sale must be reported on that year’s tax return.
I moved out two years ago: is the sale still exempt?
The home you left remains exempt if sold by 31 December of the year after you moved, or later if you have no other home available. Otherwise the 5-year rule applies.
How is the capital gain on property calculated in Luxembourg?
Sale price minus selling costs, minus the acquisition price (purchase, costs and works). If you held the property for more than five years, the acquisition price is multiplied by the revaluation coefficient for the purchase year, then the €50,000 allowance (€100,000 for a couple) is deducted. Half the global rate applies to the rest.
What is the speculation period for property in 2026?
Five years between the date of the purchase deed and the date of the sale deed. The two-year period was a temporary measure for sales until 30 June 2025 (30 September 2025 with a sale agreement registered before 30 June 2025).
What is the half global rate?
The average tax rate on all your income for the year, including the gain, is calculated, and half of it is applied to the gain. The maximum is therefore 21%, plus the employment fund contribution (7% or 9% of the tax).
Which revaluation coefficients apply in 2026?
Those of the 2026 budget law, which replace the previous table from tax year 2026. Examples: 2.05 for 1990, 1.65 for 2000, 1.33 for 2010, 1.06 for 2022, 1.00 from 2024.
Is the agency commission deductible?
Yes. Costs directly linked to the sale and paid by the seller, such as agency commission, are deducted from the sale price.
Do you pay tax on selling your main residence?
No, if the conditions of art. 102bis L.I.R. are met: you lived there since buying it or during the five years before the sale, or moved out for family or work reasons. The sale must still appear on your tax return.
How is inherited property taxed?
The base is not the value at death but the price paid by the last buyer (your parents, for instance), revalued with that year’s coefficient. If it was their last main residence, an extra €75,000 allowance applies.
When is the tax paid?
The gain is declared in the tax return for the year of the sale. The tax is due with the tax assessment, sometimes as quarterly advance payments set by the tax office.
Further tools
Guides
 Marc KreitzFounder of the iMMOSOLUTIONS agency in Howald since 2006, Marc Kreitz builds tools that make the Luxembourg property market easier to understand: valuation, notary fees, capital gains.marckreitz.lu